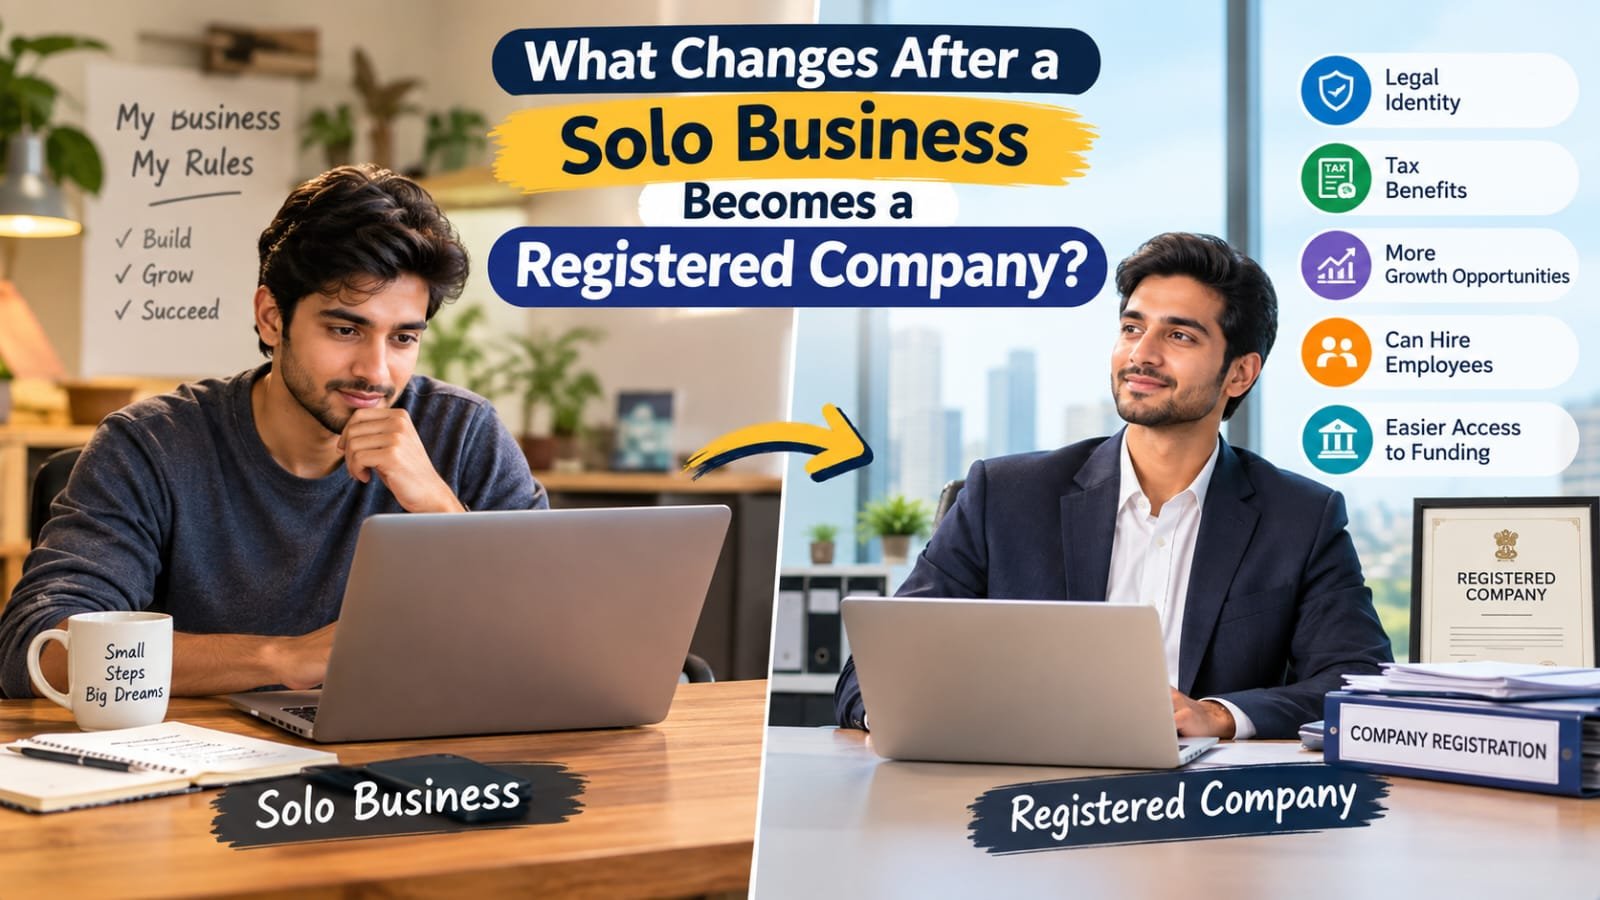
Many founders in India run a business for years as a proprietorship before they think seriously about legal registration. On the day after incorporation, the work usually looks identical. The legal position of the owner, however, has changed completely. As of 31 May 2026, India had 31,44,835 registered companies on record, of which 97,706 were One Person Companies. It remains a minority structure, yet a steady one for solo founders who want limited liability without adding a second shareholder.
The second change is administrative. Informal record-keeping ends. OPC compliance runs on a fixed statutory calendar under the Companies Act, 2013, and the calendar applies even in a year with no revenue at all. Founders who understand this before incorporation usually find the transition orderly.
The Business Becomes a Separate Legal Person
A proprietorship has no identity apart from the proprietor. A One Person Company, recognized under Section 2(62) of the Companies Act, 2013, holds its own assets, signs its own contracts, and operates its own bank account. The liability of the member is limited to the amount unpaid on the shares, so personal property stays protected unless the founder has given a personal guarantee or the matter involves fraud.
One condition is specific to this structure. The member must name a nominee in the memorandum, and that nominee steps in as member if the founder dies or becomes incapable of contracting.
Company Money Stops Being Personal Money
Withdrawals can no longer be casual transfers. Money leaves the company as director remuneration, as dividends, or as a properly documented loan, and each route carries its own tax treatment. Books of account, board minutes, and statutory registers must be maintained at the registered office throughout the year.
A Filing Calendar Replaces Informal Practice
The annual obligations of a One Person Company registration are lighter than those of a private limited company, but they are firm:
- Form AOC-4, carrying the audited financial statements, is due within 180 days from the close of the financial year. For FY 2025-26, that date was 27 September 2026.
- Form MGT-7A, the simplified annual return for OPCs and small companies, follows within 60 days of the deemed annual general meeting date, which fell in late November 2026.
- Form ADT-1 reports who the statutory auditor is. Size does not excuse anyone here. A company that earned nothing all year is audited on the same terms as one that earned crores.
- Form ITR-6 carries the income tax return. Where the audit requirement applies, as it does for every OPC, the return was due by 31 October 2026.
- DIR-3 KYC used to be an annual chore for the director. Rules notified on 31 December 2025 and effective from 31 March 2026 changed that to once in three financial years, verified by 30 June of the year that follows the third one.
Delay carries a cost. Late filing of AOC-4 or MGT-7A attracts an additional fee of ₹100 per day, per form, with no upper ceiling. An OPC is exempt from holding an annual general meeting under Section 96(1). Resolutions of the sole member are simply entered and signed in the minutes book as provided in Section 122.
Taxation Shifts From Slab Rates to Company Rates
A proprietor pays tax at individual slab rates on business income. A company is assessed separately. Under the concessional corporate regime, the base rate of 22%, with a flat surcharge of 10% and cess of 4%, produces an effective rate of 25.17% at every income level. The Income-tax Act, 2025 replaced the 1961 law with effect from 1 April 2026, applicable from FY 2026-27, though the corporate rates themselves were carried forward unchanged.
Growth is No Longer Capped
Earlier rules forced conversion once paid-up capital crossed ₹50 lakh or average turnover crossed ₹2 crore. Those ceilings were removed with effect from 1 April 2021, along with the two-year waiting period before voluntary conversion. An OPC may now continue indefinitely at any size and may convert whenever the founder chooses.
Incorporation does not make a business larger. It makes it accountable, and accountability is what lenders, clients, and investors read first.